If you were involved in a car accident in Texas, your next steps generally depend on who was at fault, whether anyone was injured, what insurance coverage applies, and what evidence is available.
Before accepting a settlement or signing anything, understand your claim, available coverage, potential damages, and applicable deadlines. Texas operates under an at-fault insurance system, meaning the driver who caused the crash is financially responsible for resulting damages. This guide walks you through every critical decision point—from the scene of the crash to the settlement table—so you can make informed choices about your legal options.
Quick Navigation
-
What to do after a Texas car accident
-
When you may need a lawyer
-
How Texas insurance claims work
-
What damages may be available
-
How much a lawyer costs
-
Texas lawsuit deadlines
-
Common accident types
-
Frequently asked questions
What Should You Do After a Car Accident in Texas?
The actions you take in the first hours and days after a crash can significantly impact your ability to recover compensation. Texas law requires specific steps, and insurance companies will scrutinize your behavior for any reason to reduce or deny your claim.
Move to a Safe Location
If your vehicle is operable and it is safe to do so, Texas law requires you to move your car off the main lanes of traffic to prevent further accidents. Turn on your hazard lights and move to the shoulder or a nearby parking lot. If the vehicle cannot be moved, stay inside with your seatbelt fastened and call for help.
Call 911 When Appropriate
Texas law requires you to call police if the accident resulted in injury, death, or property damage exceeding a certain threshold. Even for minor collisions, having an official police report creates a valuable record that insurance adjusters cannot easily dispute. When officers arrive, provide factual information about what happened—but avoid speculating about fault or apologizing, as those statements can be used against you later.
Exchange Insurance and Driver Information
Texas law requires each driver to exchange driver and insurance information with other involved parties. Collect the other driver’s name, phone number, insurance company name, policy number, and a photograph of their insurance card. If they refuse to provide this information, note that refusal—it may become relevant if you need to pursue an uninsured motorist claim.
Photograph the Accident Scene
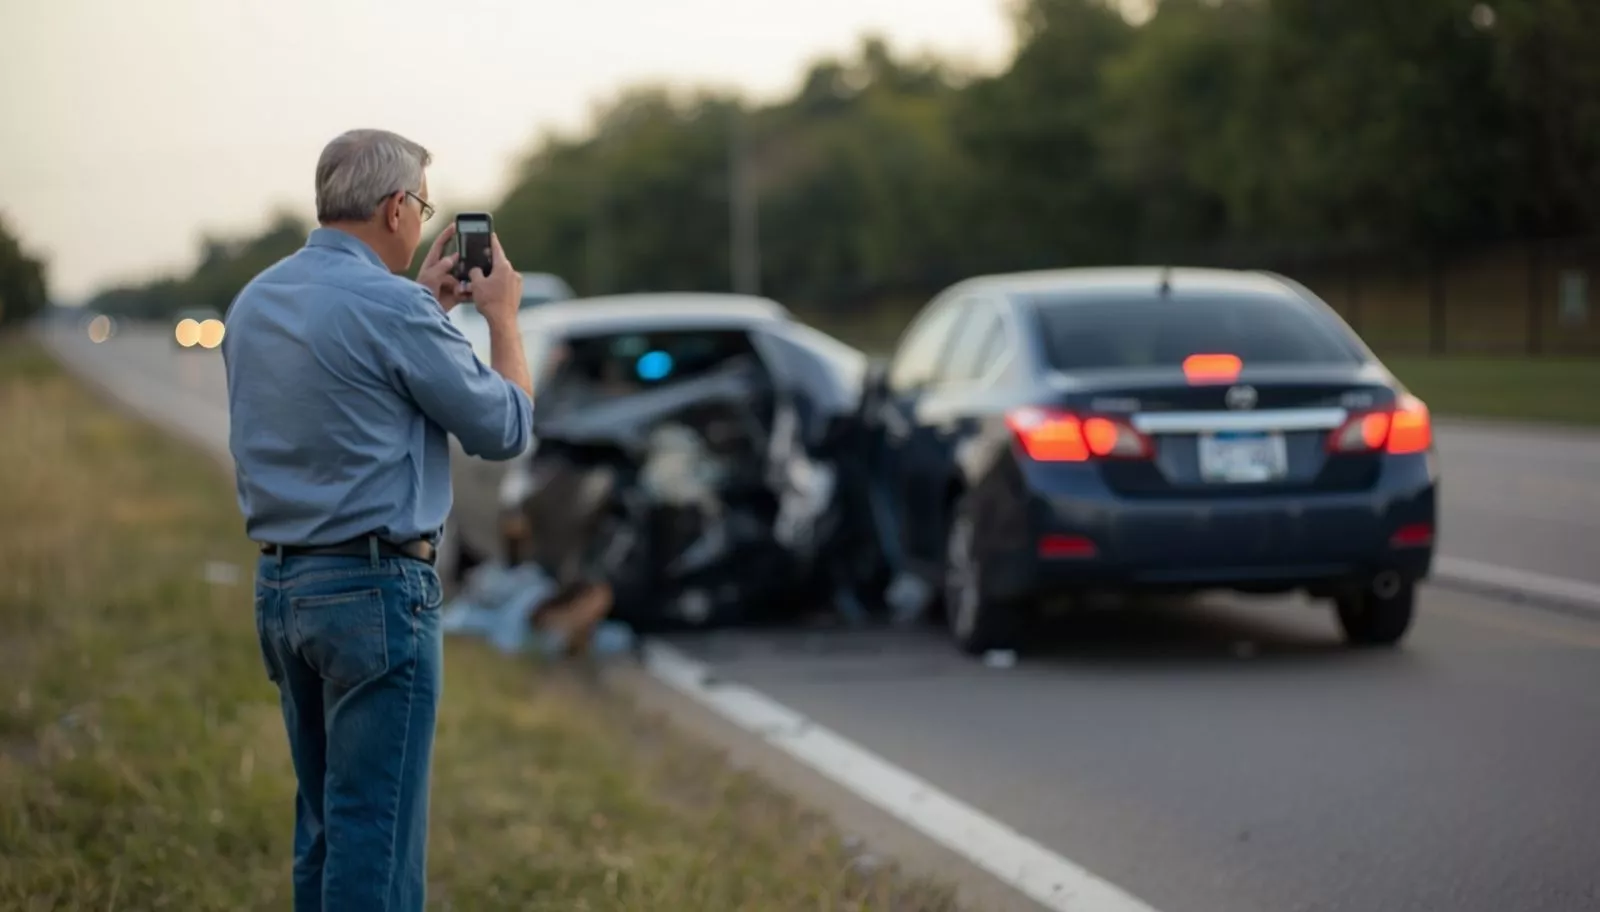
Take photographs of all vehicles involved from multiple angles, capturing license plates, damage patterns, road conditions, traffic signals, and the position of the vehicles relative to each other. These images preserve evidence that may be crucial if the other driver later disputes how the crash occurred. Photograph any visible injuries as well—bruises, cuts, and swelling can fade before you have a chance to document them officially.
Collect Witness Information
Get names and contact information from any witnesses who saw the crash. Independent witnesses can be powerful evidence if fault is disputed. If witnesses mention having dashcam footage or if you notice nearby surveillance cameras, make note of their locations—that footage may only be available for a limited time.
Get the Crash Report
Texas law enforcement agencies file crash reports through the Texas Department of Transportation’s crash records system. A copy of the collision report should be available approximately 10 days after the crash from the investigating police department or online through the state’s crash records portal. This official report typically includes officer observations about contributing factors, witness statements, and a diagram of the collision.
Seek Medical Attention When Necessary
Even if you feel fine immediately after the crash, seek a medical evaluation. Adrenaline can mask pain and injury symptoms for hours or even days. Conditions like whiplash, concussions, and internal injuries may not become apparent until later. Beyond your health, medical records created close in time to the crash provide objective evidence linking your injuries to the accident—something insurance adjusters demand before paying claims.
Notify Your Insurance Company
Most Texas auto policies require “prompt notice” of any accident, typically within 30 days. Report the crash to your own insurer even if the other driver was clearly at fault. This protects your rights under your own policy, including uninsured motorist coverage if the at-fault driver has insufficient insurance. When reporting, stick to facts about what happened and the damage involved—do not discuss fault or the extent of your injuries with your insurer’s representative beyond basic information.
Read also: Car Insurance Quotes in Austin Texas
When Should You Consider Talking to a Texas Car Accident Lawyer?
Not every fender-bender requires legal representation. However, certain circumstances dramatically increase the value of having an attorney advocate for you.
You Suffered Significant Injuries
If your injuries required emergency treatment, hospitalization, surgery, or ongoing medical care, the stakes of your claim justify legal involvement. Medical bills for even a moderate injury can easily exceed the minimum liability coverage most Texas drivers carry. An attorney can identify all available insurance coverage sources and pursue compensation beyond just the at-fault driver’s policy limits.
Fault Is Disputed
When both drivers blame each other, insurance companies rely on disputed fault to delay or deny claims. Texas follows a modified comparative fault rule: you can recover damages if you are 50% or less at fault, but your compensation is reduced by your percentage of responsibility. If you are found more than 50% at fault, you recover nothing. An attorney can gather evidence, interview witnesses, and present your case in a way that minimizes your assigned fault percentage.
The Insurance Company Denied Your Claim
A denial does not necessarily mean you have no case. Insurance adjusters sometimes deny valid claims hoping the injured person will give up. Common wrongful denial reasons include disputed liability, pre-existing conditions, or alleged failure to seek timely medical treatment. An attorney can review the denial letter, identify the insurer’s reasoning, and challenge it with supporting evidence.
The Settlement Offer Seems Inadequate
Insurance adjusters often make quick, low offers before you fully understand the extent of your injuries and future medical needs. Once you accept a settlement, you generally cannot reopen the claim for additional compensation if your condition worsens. An attorney can evaluate whether an offer accounts for future medical care, lost earning capacity, and the full impact of your injuries on your life.
The Accident Involved Multiple Vehicles
Multi-vehicle collisions create complex liability questions. Establishing which driver caused the chain-reaction crash and how fault should be apportioned among multiple defendants requires accident reconstruction and careful evidence analysis. Without clear liability, insurance companies may point fingers at each other while you wait for compensation.
The Other Driver Was Uninsured
Texas has one of the highest uninsured driver rates in the country. If you were hit by an uninsured driver, your recovery may depend on your own uninsured/underinsured motorist coverage. UM/UIM claims involve different procedures and requirements than standard liability claims, and insurers often scrutinize these claims more aggressively.
A Commercial Vehicle Was Involved
Accidents involving trucks, delivery vans, or other commercial vehicles introduce additional legal issues: federal motor carrier regulations, employer liability, corporate insurance policies, and potentially multiple defendants. Commercial carriers have teams of attorneys and investigators working to minimize their exposure from the moment a crash occurs. You need comparable resources on your side.
The Accident Caused Substantial Lost Income
If your injuries prevented you from working or reduced your future earning capacity, those losses are recoverable damages. Proving lost income and diminished earning capacity requires documentation from your employer, tax returns, and sometimes expert testimony. An attorney can calculate the full economic impact of your injuries and demand compensation accordingly.
You May Have a Permanent Injury
Permanent injuries—those that leave lasting impairments, chronic pain, or disfigurement—significantly increase the value of a claim but also require stronger evidence. Medical experts may need to testify about your future care needs, and life care planners can calculate the lifetime cost of your condition. These cases often involve litigation to achieve full value.
Not sure where your situation falls? Compare your accident circumstances with the checklist above before deciding what to do next.
How Does a Texas Car Accident Insurance Claim Work?
Understanding the claims process helps you anticipate what comes next and recognize when the insurance company is not acting in good faith.
Filing the Claim
You can file a claim with the at-fault driver’s insurance company or, in some situations, with your own insurer under UM/UIM or collision coverage. The claim should include basic information about the accident, the parties involved, and the nature of your injuries and damages. Insurance companies have specific claim-handling deadlines in Texas, including acknowledgment and decision timelines, though exact requirements depend on the circumstances.
Speaking with the Adjuster
After you file a claim, an adjuster will contact you to gather information. This conversation is not neutral—the adjuster’s job is to pay as little as possible. Adjusters are trained to ask questions that create inconsistencies in your account, minimize the severity of your injuries, or shift blame toward you. You are not required to give a recorded statement to the other driver’s insurer, and you should decline to do so until you have consulted with an attorney.
Documenting Vehicle Damage
The at-fault driver’s property damage liability coverage pays to repair or replace your vehicle. Obtain at least one independent repair estimate, and if the vehicle is totaled, research its fair market value using resources like Kelley Blue Book or NADA. Do not accept the insurer’s first valuation without verifying it against market data.
Documenting Medical Expenses
Keep every medical bill, explanation of benefits, and treatment record related to the accident. These documents establish the economic value of your claim. If you receive treatment through health insurance, the “billed charges” are typically higher than the “paid amounts”—and insurance companies may argue over which figure should be used. An attorney can help you navigate this dispute.
Receiving an Insurance Settlement Offer
When the adjuster makes an offer, review it carefully. Initial offers are almost always lower than what a claim is worth. The offer may account for current medical bills but ignore future treatment, lost wages, pain and suffering, or the full impact of your injuries on your daily life. You are not obligated to accept the first offer, and doing so may waive your right to additional compensation.
Negotiating a Disputed Claim
Negotiation involves presenting evidence that supports a higher valuation and explaining why the insurer’s offer is inadequate. This may include medical records, physician statements, wage loss documentation, and evidence of how the injury has affected your quality of life. Texas Department of Insurance guidance advises consumers to keep records of communications and ask insurers to identify the specific policy language supporting their settlement position.
What Happens If the Insurer Refuses to Pay?
If negotiation fails, your options include filing a lawsuit, pursuing a claim under your own UM/UIM coverage, or filing a complaint with the Texas Department of Insurance. Litigation is not always necessary—the filing of a lawsuit often prompts insurers to make more reasonable offers—but it requires an attorney experienced in Texas court procedures and local rules.
What Compensation Can a Texas Car Accident Claim Include?
Texas law allows recovery for both economic damages (financial losses with clear dollar values) and non-economic damages (subjective losses without direct financial receipts).
Medical Expenses
Past medical expenses include emergency room charges, hospital stays, surgeries, doctor visits, diagnostic imaging, prescription medications, physical therapy, and any other treatment related to the accident. Keep every bill and explanation of benefits.
Future Medical Treatment
If your injuries require ongoing care—such as future surgeries, extended rehabilitation, or lifelong medication—those costs are recoverable as future medical damages. Proving future medical needs typically requires a physician’s testimony about your prognosis and treatment plan.
Lost Wages
Wages you lost while recovering from your injuries or attending medical appointments are recoverable. Documentation should include pay stubs, employer statements, and tax returns showing the income you would have earned.
Reduced Earning Capacity
If your injuries limit the work you can perform or the income you can earn in the future, you can recover damages for diminished earning capacity. This is distinct from lost wages—it compensates for your reduced ability to earn over your remaining career. Vocational experts and economists often provide evidence supporting these claims.
Vehicle Damage
Property damage damages cover the cost to repair your vehicle or, if it was totaled, its fair market value immediately before the crash. You may also recover for damage to personal property inside the vehicle.
Rental Vehicle Expenses
While your vehicle is being repaired or replaced, rental car costs may be recoverable. Check whether the at-fault driver’s policy includes rental reimbursement coverage, or whether your own policy provides it.
Pain and Suffering
Pain and suffering damages compensate for physical pain, mental anguish, emotional distress, and the loss of enjoyment of life caused by the accident. Unlike medical bills, these damages do not have a simple formula—their value depends on the severity of your injuries, the duration of your recovery, and how the accident has changed your daily life.
Other Potentially Recoverable Losses
Additional damages may include:
-
Disfigurement or scarring from accident-related injuries or surgeries
-
Loss of consortium for a spouse who has lost companionship and support
-
Punitive damages in cases involving gross negligence or intentional misconduct
How Much Is a Texas Car Accident Claim Worth?
Why There Is No Single Texas Settlement Amount
Any website promising an “average settlement” for Texas car accidents is misleading you. Every claim depends on unique facts: the severity of your injuries, the amount of available insurance coverage, whether fault is disputed, and how convincingly your damages can be documented.
Some data suggests settlements nationwide may average between $20,000 and $30,000, but actual Texas settlements range from a few thousand dollars for minor soft tissue injuries to millions of dollars for catastrophic injuries or wrongful death.
Injury Severity
Minor injuries that heal relatively quickly with conservative treatment typically result in lower settlements. Severe injuries—traumatic brain injuries, spinal cord damage, fractures requiring surgery, or permanent disabilities—command significantly higher compensation because they involve greater medical costs, longer recovery periods, and lasting impacts on quality of life.
Medical Treatment
The total cost of your medical care, including future treatment, forms the foundation of your economic damages. Insurers scrutinize medical records for gaps in treatment (which they argue indicate the injury was not serious) and pre-existing conditions (which they argue explain your symptoms).
Insurance Limits
The at-fault driver’s liability insurance policy limits the amount you can recover from that driver. Texas requires minimum coverage of $30,000 per person and $60,000 per accident for bodily injury, plus $25,000 for property damage. If your damages exceed these limits, your attorney may identify other coverage sources—such as UM/UIM coverage on your own policy, commercial policies, or additional liable parties.
Liability
If you share fault for the accident, your compensation is reduced proportionally under Texas’s modified comparative fault system. For example, if you are found 20% at fault and your total damages are $100,000, you would recover $80,000. If your fault exceeds 50%, you recover nothing.
Lost Income
Lost wages and reduced earning capacity directly increase the value of a claim. Higher-income earners with documented income losses typically have more valuable claims, though insurers may challenge the extent of those losses.
Long-Term Consequences
Permanent injuries, chronic pain conditions, and injuries that require lifelong care or limit your ability to work have substantially higher value than injuries with full recovery. Life care planners and medical experts help quantify these long-term costs.
Evidence Supporting the Claim
The quality of your evidence matters as much as the nature of your injuries. Prompt medical treatment, consistent follow-up care, witness statements, photographs, and expert testimony all strengthen a claim’s value. Weak evidence gives insurers grounds to dispute or minimize damages.
How Much Does a Car Accident Lawyer Cost in Texas?
What Is a Contingency Fee?
Most Texas car accident attorneys work on a contingency fee basis, meaning you pay nothing upfront and the attorney’s fee comes as a percentage of your settlement or court award. If you recover nothing, you owe no attorney fees.
When Does the Lawyer Get Paid?
Your attorney receives payment when your case resolves—either through settlement or a court judgment. The fee percentage is deducted from the gross recovery before you receive your portion.
Typical Contingency Fee Percentages
In Texas, contingency fees for car accident cases generally range from 33% to 40% of the total recovery:
-
Pre-suit settlement: Typically around 33%
-
Post-suit settlement: Often 35% to 40% once litigation begins
-
Trial or appeal: May increase further depending on complexity
The exact percentage depends on the firm, the case complexity, and whether litigation becomes necessary. Your fee agreement should clearly state how the percentage changes at each stage.
What Case Expenses Might Apply?
Attorney fees are separate from case costs. Case expenses are the out-of-pocket costs your attorney advances to build your claim, including:
-
Court filing fees
-
Medical record retrieval costs
-
Expert witness fees
-
Deposition costs and court reporter fees
-
Investigation and evidence-gathering expenses
Most firms deduct case costs from the settlement before calculating the attorney’s fee percentage. Ask your attorney whether costs come out before or after the fee calculation—that distinction affects your final recovery.
What Happens If There Is No Recovery?
Under a true contingency fee arrangement, you owe no attorney fees if there is no recovery. Some fee agreements require clients to repay advanced case costs even if the case is unsuccessful, so read the agreement carefully before signing.
Questions to Ask Before Signing a Fee Agreement
-
What percentage will you charge if the case settles before a lawsuit is filed?
-
What percentage applies if litigation becomes necessary?
-
Are case costs deducted before or after your fee percentage?
-
What happens if I lose?
-
How will I receive updates about my case?
-
Who will handle my case day-to-day?
Texas requires that all contingency fee agreements be in writing and signed by both the client and the attorney.
How Long Do You Have to Sue After a Texas Car Accident?
Texas Personal-Injury Deadline
Texas law sets a two-year statute of limitations for personal injury lawsuits arising from car accidents. This means you must file a lawsuit within two years of the accident date, or you likely lose your right to sue entirely.
Insurance Claim vs. Lawsuit Deadline
The two-year statute of limitations applies to filing a lawsuit, not to filing an insurance claim. You can file an insurance claim immediately after the accident, but if negotiations fail and you need to sue, the two-year deadline still applies. Starting your case early gives your attorney more time to gather evidence and build a strong claim.
Wrongful-Death Claims
If a person dies from accident-related injuries, the two-year period typically begins from the date of death, not the accident date. This can effectively extend the deadline if the death occurred sometime after the crash.
Claims Involving Government Entities
If a government vehicle or employee was involved in the accident, the timeline is dramatically shorter. Texas law requires formal written notice to the governmental unit—often within 45 days for cities like Plano, though the specific deadline depends on the entity. The Texas Tort Claims Act governs these claims and includes additional procedural requirements. Missing the notice deadline bars the lawsuit even if you file within two years.
Why Exceptions Matter
Several exceptions can extend or complicate the deadline:
-
Minors: The statute does not begin until the injured person turns 18
-
Mental incapacity: The deadline may be tolled for someone unable to manage their affairs
-
Discovery rule: In limited circumstances, the deadline may begin when the injury is discovered rather than when the accident occurred
These exceptions have strict requirements and should not be relied upon without attorney guidance. The safe assumption is that you have two years from the accident date—and that waiting reduces the evidence available to support your claim.
Important: This section provides general information about Texas law and does not constitute personalized legal advice. Consult a Texas attorney about how the statute of limitations applies to your specific circumstances.
Common Types of Texas Car Accident Claims
Rear-End Collisions
Rear-end crashes are among the most common accident types. Liability often focuses on the rear driver, but exceptions exist—such as when the front driver reversed suddenly or had defective brake lights.
Head-On Collisions
Head-on crashes typically cause the most severe injuries due to the combined force of both vehicles. These cases often involve disputed liability, requiring accident reconstruction evidence.
T-Bone Accidents
Side-impact collisions at intersections frequently involve right-of-way disputes. Traffic signals, stop signs, and witness testimony become critical evidence.
Hit-and-Run Accidents
When the at-fault driver flees, recovery may depend on your own UM/UIM coverage. Texas law requires physical contact between vehicles for UM claims in unknown-driver situations, though this rule has exceptions.
Uninsured-Driver Accidents
Texas’s high uninsured driver rate makes UM/UIM coverage essential. If you rejected this coverage in writing, your options may be limited to your collision coverage for vehicle damage and your health insurance for medical bills.
Uber and Rideshare Accidents
Rideshare accidents involve complex insurance questions. Uber and Lyft carry contingent liability coverage that applies depending on the driver’s status at the time of the crash (app on, en route, or transporting a passenger).
Distracted-Driving Crashes
Texting, phone use, and other distractions are common causes of accidents. Cell phone records can provide powerful evidence of distraction, but they require preservation letters to prevent deletion.
Drunk-Driving Crashes
Drunk-driving accidents may support claims for punitive damages in addition to compensatory damages. The criminal DWI case can provide evidence for the civil claim, though the burden of proof is lower in civil court.
Multi-Vehicle Collisions
Chain-reaction crashes on Texas highways create complex liability questions involving multiple drivers, multiple insurance policies, and disputed sequences of events.
What If the Other Driver Doesn’t Have Insurance?
Uninsured Motorist Coverage
Uninsured motorist (UM) coverage on your own policy pays for injuries caused by a driver with no liability insurance. Texas insurers must offer UM coverage, though drivers can reject it in writing.
Underinsured Motorist Coverage
Underinsured motorist (UIM) coverage applies when the at-fault driver’s liability limits are insufficient to cover your damages. For example, if the other driver has minimum coverage but your medical bills exceed that amount, your UIM coverage may pay the difference up to your policy limits.
Hit-and-Run Accidents
UM coverage typically applies to hit-and-run accidents, though Texas law generally requires physical contact between vehicles for UM claims involving unknown drivers. Exceptions exist, and your attorney can advise whether your specific circumstances qualify.
Collision Coverage
Collision coverage pays to repair or replace your vehicle regardless of who caused the accident. This coverage applies even in hit-and-run crashes where the at-fault driver is never identified.
Medical Payments Coverage
MedPay coverage pays medical bills for you and your passengers regardless of fault, up to your policy limits. This coverage can provide immediate funds for treatment while a liability claim is pending.
What If the Insurance Company Denies Your Claim?
Ask Why the Claim Was Denied
Insurance companies must provide a reason for denial. Common reasons include disputed liability, alleged pre-existing conditions, gaps in medical treatment, or a determination that the accident did not cause your injuries.
Review the Policy Language
Request a copy of the at-fault driver’s policy and identify the provisions the insurer cites in its denial. Texas Department of Insurance guidance advises consumers to ask insurers to identify the specific policy language supporting their position.
Gather Supporting Evidence
Medical records linking your injuries to the accident, witness statements, photographs, and expert opinions can counter the insurer’s denial rationale. An attorney can identify what evidence is missing and obtain it efficiently.
Challenge an Inadequate Settlement
If the insurer makes a low offer rather than denying outright, you can challenge it with documentation showing the claim is worth more. Negotiation often resolves disputes without litigation.
When to Seek Legal Assistance
If the insurer denies a valid claim, engages in bad-faith practices, or refuses to negotiate reasonably, an attorney can file a lawsuit and pursue damages including attorney’s fees in some circumstances.
Texas Car Accident FAQ
Do I need a lawyer after a car accident in Texas?
Not always. Minor accidents with clear liability and minor injuries can often be resolved without an attorney. However, you likely need a lawyer if you suffered significant injuries, fault is disputed, the insurance company denied your claim, or the settlement offer seems inadequate.
How much does a car accident lawyer cost in Texas?
Most Texas car accident lawyers work on contingency, charging 33% to 40% of the recovery. You pay nothing upfront, and if there is no recovery, you owe no attorney fees.
How long do I have to sue after a car accident in Texas?
Two years from the accident date for personal injury lawsuits. Government claims may have notice deadlines as short as 45 days. Wrongful death claims run from the date of death.
How much is a car accident settlement in Texas?
There is no typical amount. Settlements range from a few thousand dollars for minor injuries to millions for catastrophic injuries. The value depends on injury severity, medical costs, lost income, insurance limits, and liability.
What happens if the other driver has no insurance?
Your uninsured motorist coverage may pay your damages if you purchased it. Collision coverage can pay for vehicle repairs regardless of fault. Texas requires insurers to offer UM/UIM coverage, though it can be rejected in writing.
Should I talk to the other driver’s insurance company?
You are not required to give a recorded statement to the other driver’s insurer. Adjusters are trained to minimize payouts, and statements you make can be used against you. Consider consulting an attorney before speaking with the other driver’s insurance company.
Who pays medical bills after a car accident?
Initially, your own health insurance, MedPay coverage, or PIP coverage may pay medical bills. Ultimately, the at-fault driver’s liability insurance should cover accident-related medical expenses, but this often happens through a settlement at the end of the claim rather than as bills accumulate.
What happens if both drivers are partly at fault?
Texas follows modified comparative fault. You can recover damages if you are 50% or less at fault, but your compensation is reduced by your percentage of responsibility. If you are more than 50% at fault, you recover nothing.
Can I sue after accepting an insurance settlement?
Generally, no. Accepting a settlement typically releases the at-fault driver and their insurer from further liability. This is why you should not accept a settlement until you fully understand your injuries and future medical needs.
How long does a Texas car accident claim take?
Most claims settle within several months. Complex cases involving severe injuries, disputed liability, or litigation may take a year or longer. Starting early gives your attorney more time to build the strongest possible case.
Marvin Lambert
Marvin LambertMarvin Lambert is a finance professional and financial advisor specializing in lending solutions, Car Insurance, personal finance, and consumer credit education. Through his writing, he helps readers understand practical money management strategies, borrowing decisions, and financial planning concepts in simple, actionable terms.